
Construction All Risk (CAR) Insurance Malaysia: Complete Project Protection建筑工地:CAR险种如何为复杂的工程项目提供全方位兜底?
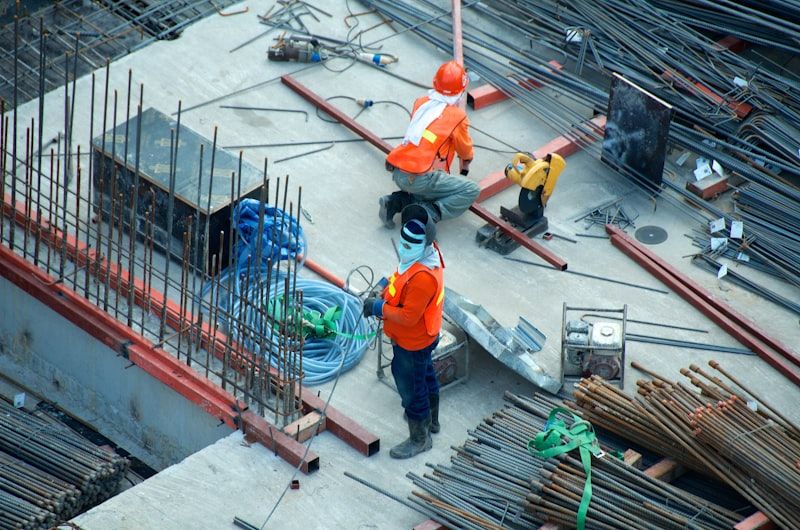
A construction site is one of the highest-risk environments in any economy. CAR insurance is not just good practice — for most Malaysian contracts, it is a contractual requirement.
建筑工地是任何经济体中风险最高的作业环境之一。建筑工程全险(CAR)不只是良好实践——对大多数马来西亚合同而言,它是合同强制要求。
What Contractors' All Risks covers
CAR is a composite policy covering two main sections: Section 1 covers physical loss or damage to the contract works (buildings under construction, temporary works, materials on-site) and contractor's plant and equipment. Section 2 covers third-party liability — injury to members of the public or damage to surrounding property caused by construction activities.
The most common CAR claims in Malaysia
The most frequent triggers on Malaysian sites are: flood damage to foundation works during the wet season (November-January), theft of copper wiring and metal scaffolding, crane collapse causing third-party property damage, and worker injury from scaffolding collapse. The third-party claims are often the most financially severe.
What CAR does NOT cover
Design errors (Professional Indemnity responds), defective materials or workmanship not resulting in damage to other parts of the works, consequential losses (liquidated damages for project delay), and war or terrorism. Ensure your professional team has PI cover separate from the project CAR policy.
Subcontractors: the hidden risk
Main contractors are routinely held liable for subcontractors' work under Malaysian construction law. Either require every subcontractor to carry their own CAR/liability cover and provide certificates of insurance, or ensure your master CAR policy explicitly extends to cover all subcontractors working under you.
承建商全险涵盖什么
CAR是一种综合保单,涵盖两大部分:第一部分承保合同工程的物理损毁(在建建筑、临时工程、现场物料)及承包商的工厂和设备;第二部分承保第三方责任——因施工活动导致公众受伤或周边财产损毁。
马来西亚最常见的CAR理赔
马来西亚工地最常见的触发事件包括:雨季(11月-1月)基础工程遭受洪水损害、铜线和金属脚手架被盗、吊塔倒塌导致第三方财产损失,以及脚手架倒塌导致工人受伤。其中,第三方索赔往往在财务上最为严重。
CAR不涵盖什么
设计错误(由专业责任险承保)、本身存在缺陷的材料或工艺(未波及工程其他部分的)、间接损失(工程延误违约金),以及战争或恐怖袭击。确保您的专业团队持有独立于项目CAR保单的专业责任险。
分包商:隐藏的风险
根据马来西亚建筑法律,主承包商通常须为分包商的工作承担连带责任。您可以要求每位分包商持有自己的CAR/责任险并提供保险证明,或确保您的总承包CAR保单明确扩展涵盖您名下所有分包商。
Construction insurance is complex because every project is different. A single project-specific policy review before work commences is worth far more than a generic 'contractor's policy' bought off the shelf.
建筑保险结构复杂,因为每个项目都不尽相同。施工开始前针对具体项目进行一次保单审查,其价值远超购买一份通用'承包商保单'。
Frequently asked常见问题
What does a CAR policy actually cover?CAR 工程一切险到底保什么?
CAR is a composite policy in two sections. Section 1 covers physical loss or damage to the contract works — the structure under construction, temporary works, materials on site — and the contractor's plant and equipment. Section 2 covers third-party liability for injury to the public or damage to surrounding property caused by the construction activity.CAR 是一张组合保单,分两部分。第一部分保工程本身的实体损失——在建结构、临时工程、工地材料,还有承包商的机具设备。第二部分保第三方责任——施工造成公众受伤或周边财产损坏。
What does CAR NOT cover?CAR 不保什么?
Design errors (that is Professional Indemnity's job), defective material or workmanship that has not caused damage to other parts of the works, consequential losses such as liquidated damages for project delay, and war or terrorism. Make sure the professional team carries its own PI separate from the project CAR policy.设计错误(那是 Professional Indemnity 专业责任险的事)、有缺陷但还没造成其他部分损坏的材料或工艺、间接损失例如工期延误的 LAD 罚款,以及战争和恐怖主义。专业团队要另外自己买 PI,不能靠工程的 CAR 保单。
The main contractor has CAR. Does the subcontractor still need cover?主包商买了 CAR,分包商还要买吗?
Main contractors are routinely held responsible for subcontractors' work, so the exposure does not disappear just because a CAR policy exists somewhere on the project. Whether a subcontractor is protected depends on whether it is actually named on that policy — which is worth checking in writing before work starts, not after a loss.主包商通常要为分包商的工作负责,所以工地上「有一张 CAR」不等于风险消失。分包商有没有被保到,要看它有没有真的被写进那张保单——开工前用白纸黑字确认,别等出事才查。