
Is theft covered if there was no forced entry?
Often not. Both Industrial All Risks and Burglary policies tie theft cover to forcible and violent entry or exit, or to violence against a person.
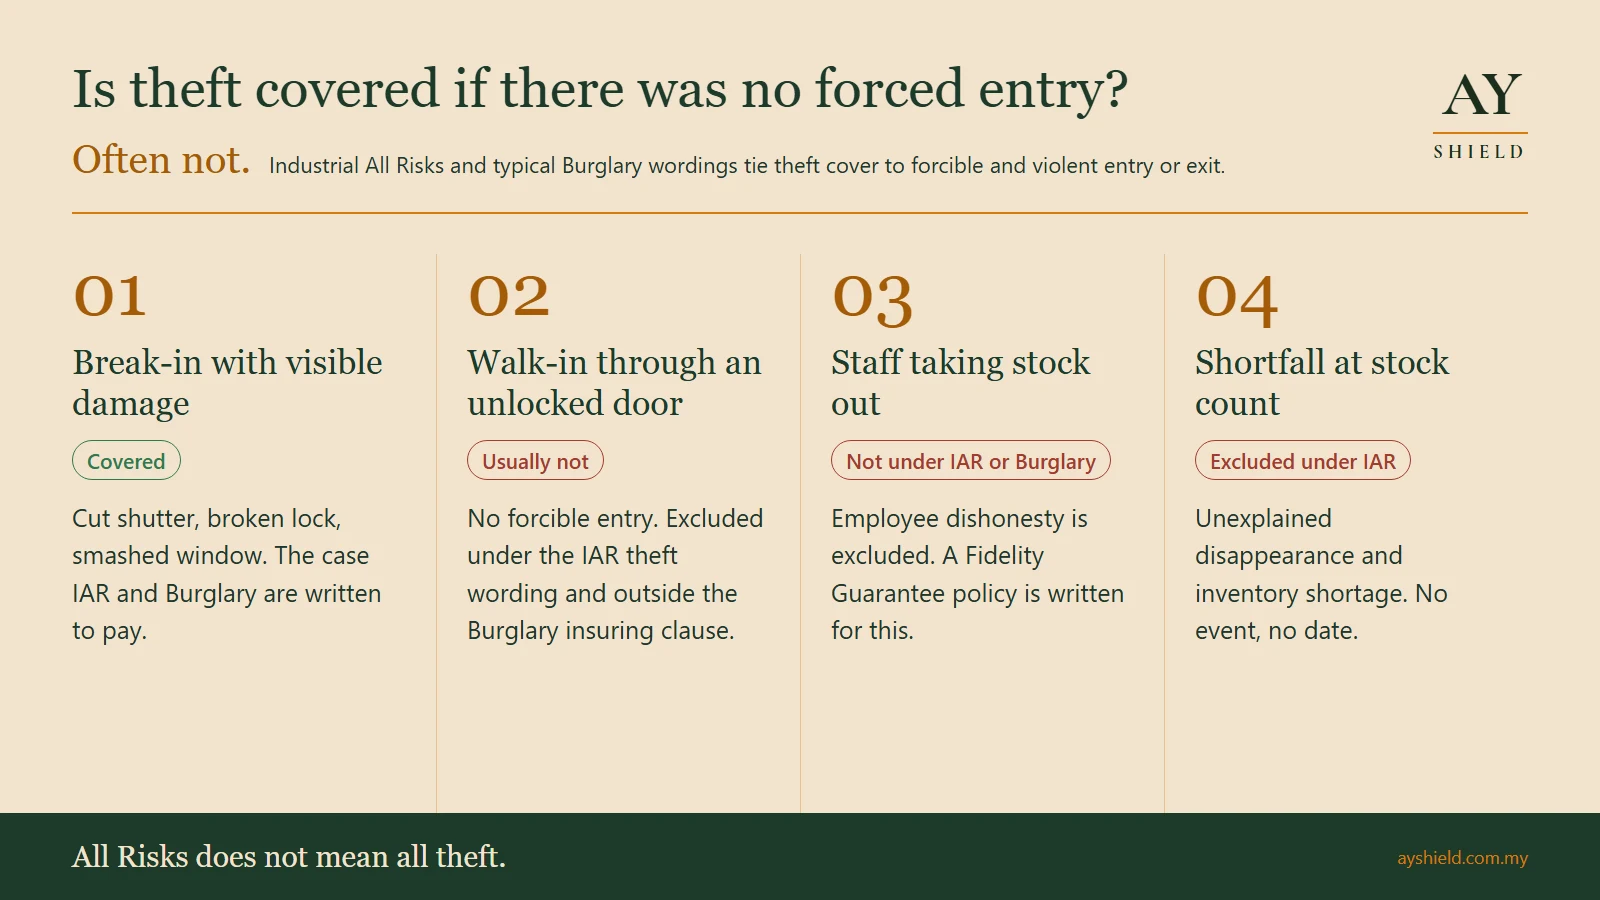
Often not. Standard Malaysian Industrial All Risks (IAR) wordings exclude theft "unless accompanied by violence or threat of violence to persons or forcible and violent entry to or exit from the Premises." A typical Burglary policy is written the same way: it pays for theft consequent upon actual forcible and violent entry or exit, armed robbery, or a person hiding on the premises. A thief who walks in through a shutter left unlocked, or a staff member who carries stock out, sits outside both. Theft by employees is the job of a separate Fidelity Guarantee policy.
All Risks does not mean all theft
An IAR policy is written the other way round from a fire policy. Instead of listing what it covers, it covers accidental physical loss or damage from any cause that is not excluded. That is why owners who move from a fire policy to IAR often assume theft is now included. It is, but only one kind of theft. The exclusions list takes the rest back out.
"theft unless accompanied by violence or threat of violence to persons or forcible and violent entry to or exit from the Premises"
The same group of exclusions goes further. It also removes loss from any fraudulent scheme, trick or false pretence practised on the insured, acts of infidelity or dishonesty by the insured or any employee, and unexplained disappearance or inventory shortage. Those are the three ways most business stock actually goes missing.
A Burglary policy draws the same line
A Burglary policy is the product built for theft, so it is natural to expect it to fill the gap. It narrows it, but the test is the same. A typical Malaysian Burglary wording pays when property is lost "by Theft consequent upon actual forcible and violent entry or exit upon the said Premises," or taken by a person feloniously concealed on the premises, or through armed robbery or hold up. It then excludes theft by the insured's family, employees, or any person lawfully on the premises.
In plain terms: a broken lock, a cut shutter or a smashed window is what turns a theft into a Burglary claim. A door left open, a key that was copied, or a delivery driver who was let in, usually is not.
Four ways stock goes missing, and which policy each one needs
- Break-in with visible damage. Forcible and violent entry. This is the case both IAR and Burglary are written to pay.
- Walk-in through an unlocked door. No forcible entry. Excluded under the IAR theft wording and outside the Burglary insuring clause.
- Staff taking stock out over months. Employee dishonesty. Excluded under IAR and Burglary. A Fidelity Guarantee policy reimburses direct pecuniary loss from fraud or dishonesty committed by an employee, within its own terms.
- Numbers that do not add up at stock count. Unexplained disappearance or inventory shortage. Excluded under IAR, and hard to claim anywhere, because there is no event and no date.
If a theft does happen
The IAR claims condition requires the insured, on the happening of loss, to take steps to minimise it, give written notice to the insurer, and give notice to the police if the event is theft or suspected theft. A written claim with the particulars of what was lost follows within 30 days, or longer if the insurer allows it in writing. Photograph any damage to doors, locks and shutters before it is repaired: that damage is the evidence of forcible entry.
For theft from a construction site, where the policy is CAR rather than IAR, the rules are different. See whether theft of materials from a construction site is covered by CAR insurance.
Frequently asked
Is theft covered if there was no forced entry?
Often not. Standard Malaysian Industrial All Risks wordings exclude theft unless accompanied by violence or threat of violence to persons or forcible and violent entry to or exit from the premises. A typical Burglary policy pays for theft consequent upon actual forcible and violent entry or exit, armed robbery, or a person concealed on the premises. Theft through an unlocked door usually falls outside both.
Does Industrial All Risks insurance cover theft by employees?
No. The standard IAR wording excludes acts of infidelity or dishonesty on the part of the insured or any of the employees. A typical Burglary policy also excludes theft by employees and by anyone lawfully on the premises. Employee dishonesty is what a Fidelity Guarantee policy is written for.
Is stock missing at a stock count covered by insurance?
Generally not under a standard Industrial All Risks policy, which excludes unexplained disappearance and inventory shortage. Without a specific, dateable event, such as a break-in noticed on a particular morning, there is nothing for the insurer to investigate as a theft.
What should I do after a break-in at my business premises?
Notify the police and give written notice to the insurer straight away, take steps to limit the loss, and photograph the damage to doors, locks or shutters before any repair, because that damage is the evidence of forcible entry. Under a standard IAR wording the written claim with particulars of the loss is due within 30 days unless the insurer allows longer in writing.
Under standard Malaysian wordings, theft cover turns on forcible and violent entry or exit, or violence against a person. IAR excludes the rest of theft, including staff dishonesty and unexplained stock loss, and a Burglary policy draws the same line. If staff theft is the real risk in your business, that is a Fidelity Guarantee question, not a Burglary one.
Clause references are to the standard Industrial All Risks wording and typical Burglary and Fidelity Guarantee wordings in use in Malaysia. Your own policy schedule and endorsements can differ, and the wording that governs your claim is the one attached to your policy. This page is general information, not advice on a specific claim.
AY Shield is a licensed insurance advisor based in Penang, Malaysia, serving contractors across Penang Island and Seberang Perai. We specialise in Contractor All Risks (CAR), WIBA and Public Liability cover for CIDB G4–G6 building and civil contractors. Principal Advisor Au-Yang Liang-Hin has over 30 years of commercial insurance experience.
Published 29 September 2026 · Bayan Lepas, Penang