
Top 5 Causes of Factory Fires in Malaysia & How to Prevent Them制造企业必读:工厂火灾的5大常见诱因及专家预防策略
Every year, factory fires destroy businesses that took decades to build. The tragedy is that most are preventable — and most were underinsured.
每年,工厂火灾摧毁了无数花费数十年建立起来的企业。悲剧在于,大多数火灾本可预防——而且大多数企业的保障严重不足。
1. Electrical faults: the silent arsonist
Electrical faults are among the most common causes of industrial fires — faulty wiring, overloaded circuits, and aging switchgear that hasn't been inspected in years. The danger is invisible until it isn't. Schedule a licensed electrical inspection annually, and ensure your fire insurance sum insured covers the full reinstatement value of your machinery, not just book value.
2. Hot work without a permit-to-work system
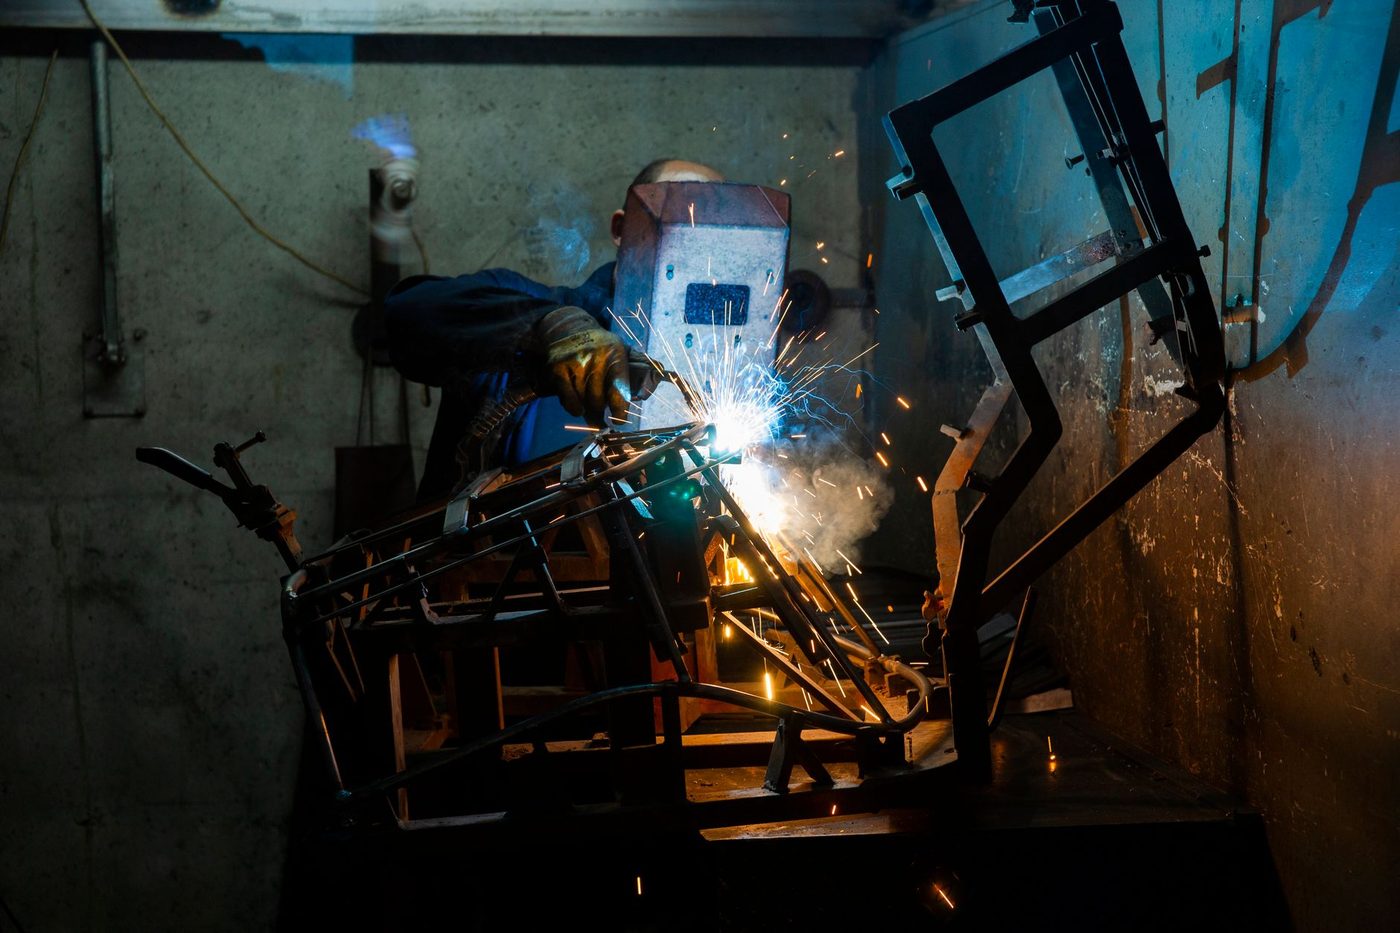
Welding, cutting, and grinding near flammable materials is the second leading cause. A formal Permit-to-Work system costs almost nothing to implement but can void an insurance claim if skipped — insurers treat undisclosed hot work as a material non-disclosure. Brief your insurer on the nature of your operations honestly.
3. Flammable liquid storage violations
Many factories store solvents, paint, or fuel far beyond permitted quantities — often in unmarked containers. A single inspection violation can trigger an insurer's 'breach of warranty' defence and result in zero payout. Store according to DOSH regulations and declare all hazardous materials on your policy schedule.
4. Lack of fire compartmentalisation
Open-plan warehouses allow fire to spread unchecked. Fire-rated walls and automatic fire doors can limit damage to a single zone. More importantly, your Business Interruption sum insured must reflect the maximum period it would take to rebuild — typically 18-24 months for a manufacturing facility, not the 12 months most policies default to.
5. No sprinkler system = higher premium AND lower payout
Insurers rate factories without sprinklers at significantly higher risk. Worse, if the Average Clause applies (sum insured below actual value), you bear a proportional share of every claim. To illustrate: a RM 2 million loss on a RM 4 million asset insured for only RM 2 million pays about RM 1 million — half the loss, yours to absorb.
1. 电气故障:隐形的纵火犯
电气故障是工业火灾最常见的起因之一——包括电线老化、电路过载和多年未检查的配电柜。危险在看不见的地方潜伏,直到一切为时已晚。建议每年聘请持牌电气工程师进行检查,并确保保险金额涵盖机器设备的全额重置价值,而非账面折旧值。
2. 未设作业许可制度的动火作业
焊接、切割和研磨作业是第二大火灾诱因。正式的“动火许可证“制度几乎零成本,但若未执行,保险公司可以“未申报高风险作业“为由拒绝理赔。请如实向保险公司申报您的业务性质,尤其是涉及动火作业的环节。
3. 违规储存易燃液体
许多工厂存放的溶剂、油漆或燃料远超法定限额,且容器未做标识。一次检查违规即可触发保险公司的“违反保证条款“抗辩,导致零赔付。请按DOSH法规存放危险品,并在保单附表中如实申报所有危险物料。
4. 缺乏防火分区
开放式仓库让火势蔓延无阻。防火隔墙和自动防火门可将损失控制在单一区域。更重要的是,营业中断险的赔偿期限须反映实际重建时间——制造业通常需要18-24个月,而非多数保单默认的12个月。
5. 无自动喷水系统 = 更高保费,更低赔付
保险公司对无喷淋系统的工厂征收更高费率。更糟糕的是,若触发比例赔偿条款(保额低于实际价值),您须自行承担相应比例的损失。一处价值400万令吉的资产只投保200万令吉,发生200万令吉损失时,实际赔付仅100万令吉。
The lesson: prevention reduces premiums, but correct sum insured and honest disclosure determine whether you actually recover. Get a policy audit before the next renewal.
教训:预防可以降低保费,但正确的保额和诚实申报才决定您是否真的能获得赔偿。在下次续保前,请进行一次保单审计。
Frequently asked常见问题
Can hot work like welding affect my fire insurance claim?焊接这类动火作业会影响火险理赔吗?
Yes. Insurers treat undisclosed hot work as material non-disclosure, which can defeat a claim. A formal permit-to-work system costs almost nothing to run, and the nature of your operations should be described to the insurer honestly at the outset rather than discovered after a fire.会。动火作业没申报,保险公司会当作重大事实未告知,理赔可能因此被拒。正式的动火准证(permit-to-work)制度几乎不花钱,作业性质应该一开始就老实告诉保险公司,不要等火烧了才被发现。
We store solvents and paint on site. Does that need to be declared?厂里存溶剂、油漆,需要申报吗?
Yes. Storing flammable liquids beyond permitted quantities, or in unmarked containers, can trigger the insurer's breach of warranty defence and result in no payout at all. Store according to DOSH requirements and list hazardous materials on the policy schedule.要。易燃液体存放超量、或装在没标示的容器里,保险公司可以主张违反保证条款,结果是一分钱都不赔。按 DOSH 规定存放,并把危险品列进保单明细。
Should my machinery be insured at book value or replacement cost?机器该按账面价值还是重置成本投保?
Replacement cost. Book value is depreciated and will not buy the machine again after a fire. Insure at full reinstatement value, and have an electrical inspection done annually by a licensed contractor — ageing switchgear and overloaded circuits are among the most common ignition points in factories.按重置成本。账面价值已经折旧,火灾后买不回同一台机器。按全额重置价值投保,另外每年请持牌电工检查一次——老化的开关柜和过载线路是工厂最常见的起火点之一。